Companies sometimes face difficult decisions. Economic challenges, site adjustments or restructuring may make it necessary to terminate employment relationships. Even a small number of employer-initiated terminations may trigger a notification obligation to the Arbeitsmarktservice (AMS).
Filter insights by:
Popular topics
Featured insights
Successfully employing people with disabilities: an overview of subsidies, the compensatory levy, wage subsidies, tax benefits and dismissal protection in Austria.
With the employee bonus scheme (“Mitarbeiterprämie”), employers may grant their employees a tax-privileged additional payment, provided that certain requirements are met. This article explains the applicable rules and the key points to consider.
Our latest insights
The 1st GT.European Football Cup 2023 will be remembered by us and all participants for a long time: In addition to the sporting performance, the focus was on team spirit and networking.
The preparation of financial statements in accordance with International Financial Reporting Standards (IFRS) is challenging.
Green House Gas (GHG) emissions are classified into categories being Scope 1, Scope 2 or Scope 3 emissions. And this is a way of grouping emissions between those created by the company and those created by its wider value chain.
Covid special regulations for cross-border telework in the EU area have ensured that the social security affiliation of a country does not change in the case of cross-border telework. These regulations are valid until 30 June 2023.
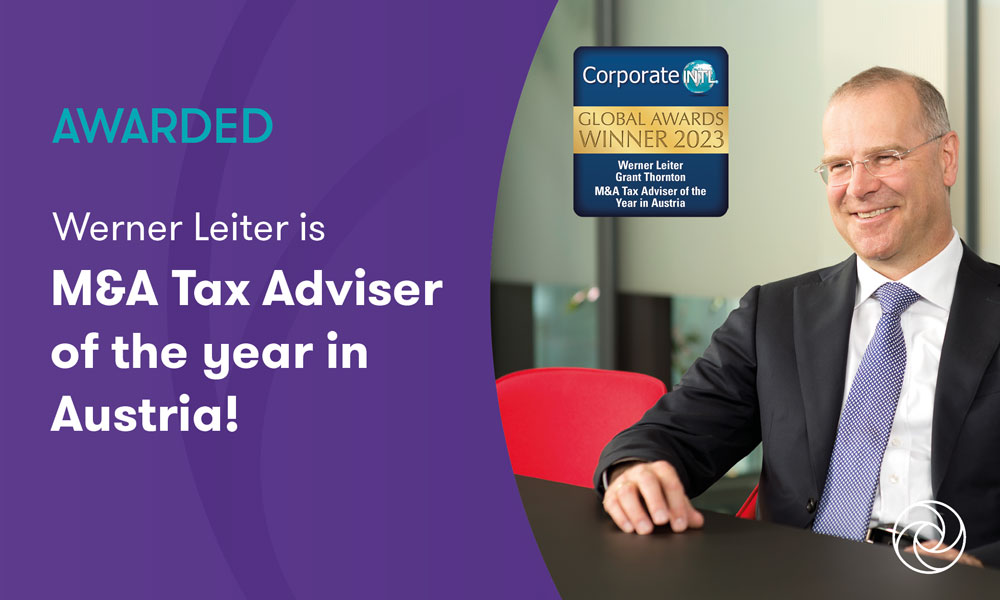
Corporate INTL's annual awards recognise the world's leading advisors and financiers in a number of countries and continents around the world.
Income that is subject to income tax is generally assessed retrospectively. This article explains when a mandatory assessment must be carried out. You can also read an update on the employee assessment without application.
In this article we inform you about the current measures and developments concerning the deductions/limits of additional earnings as of 01.01.2023, the new regulations regarding the commuter allowance and reduced public transport ticket as of 01.01.2023, and new additional triggers of mandatory personal income tax returns.
With our Tax Compliance Calendar 2023, you can see the monthly filing deadlines for Tax and Payroll at a glance. Simply download the PDF & stay on top of things all year round.
Electric vehicles are becoming increasingly popular. In connection with the acquisition of a charging device and with regard to the charging of the vehicle, there are tax and contribution law aspects to consider from a company perspective.
Our ‘Insights into IFRS 8’ series considers some key implementation issues and includes interpretational guidance in certain problematic areas. We also include several examples illustrating the Standard’s requirements.
Understanding how an entity is performing from management’s point of view during an interim reporting period can be just as important as the annual disclosures that are required when following IFRS 8 ‘Operating Segments’ – which sets out the minimum disclosure requirements for annual reporting periods.
Segmental information is a way of increasing transparency in financial statements prepared for investors and creditors, especially for areas of the business that are significant and drive the entity’s overall business strategy. IFRS 8 ‘Operating Segments’ requires this information that is provided to management to be disclosed in the annual financial statements, so that investors and other users of entities’ financial statements can review an entity’s operations from the same perspective.
Only 14% of mid-market businesses are currently reporting on the Scope 3 emissions that the International Sustainability Standards Board (ISSB) recently voted unanimously to require companies to disclose, according to new research from Grant Thornton International published ahead of COP27 in Egypt.
As part of the 2nd statutory inflation relief package, a change has been effected to reduce the employer's contribution to the Employer Family Burden Equalisation Fund (Dienstgeberbeitrag zum Familienlastenausgleichsfonds = DB) from 3.9 % to 3.7 % in the calendar years 2023 and 2024.
IFRS 3 ‘Business Combinations’ contains the requirements for transactions, which are challenging in practice.
The International Accounting Standards Board (IASB) regularly publishes new International Financial Reporting Standards (IFRS), Interpretations of Standards (IFRIC) or amendments to existing IFRS Standards.